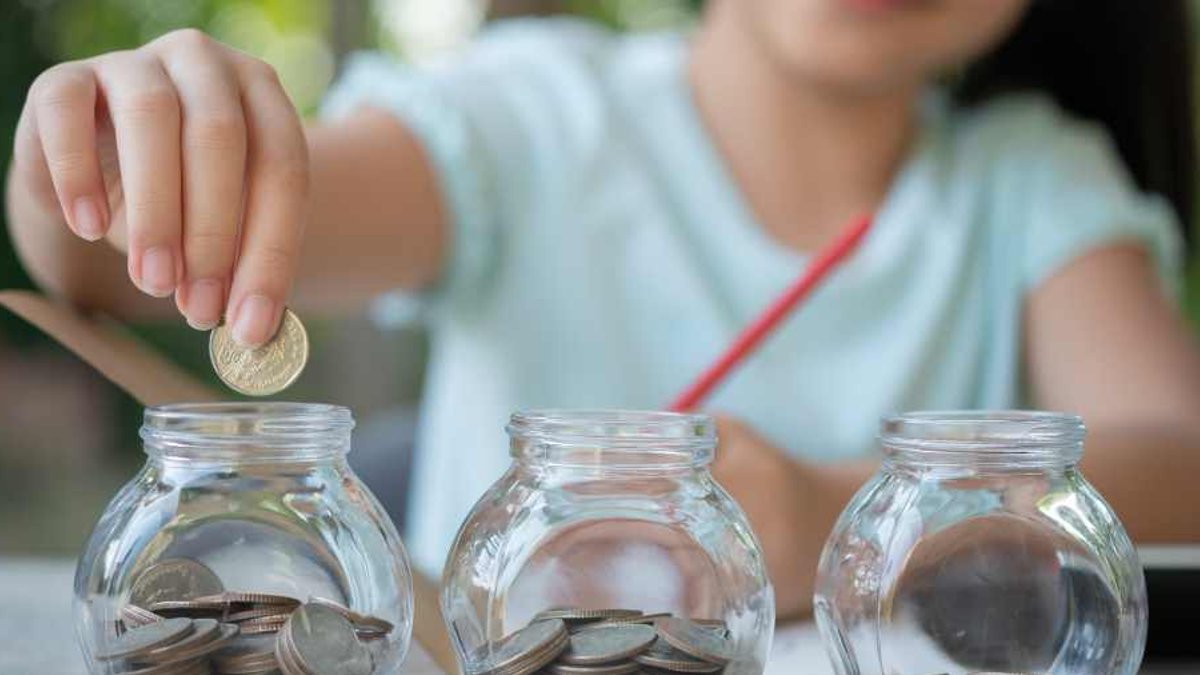
Inflation is quietly reshaping the cost of education in India, and parents are taking notice. A parent in Pune who paid ₹40,000 for a Class 1 admission a few years ago might find the same school now charging significantly more. The teaching quality remains unchanged, but the price tag has climbed. Inflation plays a critical role when planning for a child’s future education.
Education Costs Rise Faster Than Inflation
India’s retail inflation typically hovers between 4 to 6 per cent, but education costs often outpace this. Estimates suggest fees rise by 8 to 10 per cent annually, depending on the city, school board, and institution. For example, a degree costing ₹20 lakh today could reach ₹93 lakh in 20 years if fees grow at 8 per cent annually.
Tuition fees are just the beginning. Hostel bills, books, laptops, tuition classes, entrance coaching, and travel expenses quickly add up. For those considering foreign universities, currency fluctuations against the dollar or pound become an additional concern. Planning with current figures is a common mistake, as it fails to account for these escalating costs.
Savings Struggle to Keep Up with Rising Costs
Saving at 6 per cent annually while education fees rise at 8 per cent creates a widening gap. Your savings may grow, but the goal of funding your child’s education moves further away. Each year, the same amount of money covers less of the planned course. To address this, parents must rethink their approach. Calculate the projected cost of the desired course by the time your child turns 18, then determine the monthly savings needed to meet that target.
Read Also: Fashion catalog coverage is a business choice
Families need to adjust their planning strategies. Starting early, even with small amounts like ₹2,000 a month, can make a significant difference. Time allows savings to compound, but delaying reduces growth potential. Market fluctuations and steadily rising fees make early action essential.
Critical Factors in Education Planning
When comparing child education plans, focus on three key factors: inflation, education expenses, and investment duration. Use a realistic inflation rate to avoid underestimating future costs. Define your education goals, whether it’s an Indian undergraduate degree, a master’s, or a foreign university, as each has different costs. Starting early, ideally at birth, provides 18 years of compounding, while starting at age 10 leaves only 8 years.
Small adjustments can lead to significant results. Increasing contributions annually as your salary grows, even slightly, helps. Adjusting risk based on the time horizon is key. With 15 years remaining, growth-oriented investments are suitable, but with 3 years left, safer options are preferable. Review your plan annually, as both fees and family circumstances can change. If uncertain, consult a SEBI-registered adviser for guidance.

Leave a Reply